It estimates to spend Sh691 billion on developments which will mostly be funded by project loans and grants from development partners and external loans, accounting for 25 per cent. This is below the 30 per cent threshold set by the International Monetary Fund.
This is likely to force the government to borrow more to plug the budget deficit, pushing up the country’s public debt that currently stands at Sh5.3 trillion, according to latest update by the Central Bank of Kenya.
Although the Medium-Term Fiscal Framework presented to Parliament shows the country’s fiscal deficit will ease marginally to Sh607.8 billion next year compared to Sh608 billion in the current financial year, a total of Sh613.5 billion will be borrowed to plug the deficit.
“The fiscal deficit for 2019/20 will be financed by net external financing of Sh324.3 billion, domestic borrowing of Sh289.2 billion and other net domestic receipts of Sh5.7 billion,’’ the National Treasury report said.
According to the report, Treasury is targeting the budget to drop to 5.6 per cent compared to 6.1 for the current financial year that was revised upwards from 5.8 per cent. It expects to lower it further to 3.8 per cent by 2022/23.
However, the total expenditure budget is expected to rise every year to hit Sh3.57 trillion by the time President Kenyatta leaves the office in 2022.
Rising public debt
Perhaps more chilling is the total public debt that is expected to rise to Sh5.7 trillion next year before jumping to nearly Sh7.17 trillion in the year ending June 2022.
According to a plan by Treasury, debt servicing obligation is expected to rise in the next three years as more loans mature.
Cumulatively, President Kenyatta’s government will have borrowed Sh2.13 trillion in more national debts by the end of his final term in August 2022.
Debt to gross domestic ratio has been on an upward spiral in Kenya. In 2012, the country’s debt to GDP ratio was 38.2 per cent and rose by 100 basis points to reach 39.2 per cent in 2013. In 2014, debt to GDP touched 44.2 per cent, before settling at 48.8 per cent in 2015.
In 2016, debt to GDP was at 53.8 per cent before hitting an all-time high of 57.1 per cent last year. Kenya’s debt to GDP is currently at 56.2 per cent.
Even so, Treasury insists that Kenya continues to face a low risk of debt distress, as it remains below the threshold of 74 per cent of GDP in net present terms.
It is targeting debt to GDP of 48.6 per cent by June 2019 and projected to decline to 43.2 per cent of GDP by 2021.
Data released by the Institute of Economic Affairs on Wednesday last week shows that in 2017, 2018 and 2019, Kenya’s debt service to revenue ratio stood at 35.8 per cent, 30.5 per cent and 33.4 per cent respectively against the threshold of 30 per cent.
Last week, the director of debt policy at the National Treasury Haron Sirima downplayed the country’s debt situation, saying it is sustainable as it has not exceeded the 74 per cent sustainability level.
In October last year, the IMF said Kenya’s risk of defaulting on debt repayments had increased to moderate from low, citing the government’s public investment drive and revenue shortfalls in recent years.
According to the Annual Public Debt Management Report 2018 by Parliament, the growth in Kenya’s debt over the years has been on account of little improvement in the budget primary deficit, increase in debt service payments, yearly revenue shortfalls and weak commitment to fiscal consolidation over the medium term.
The Parliamentary Investment Committee workshop meeting in Mombasa over the weekend also added its voice to the growing concerns about surging public debt.
Related reporting
More Entertainment →
SportyBet Kenya Bonus for January 2026 - Uncover Unique Offers!
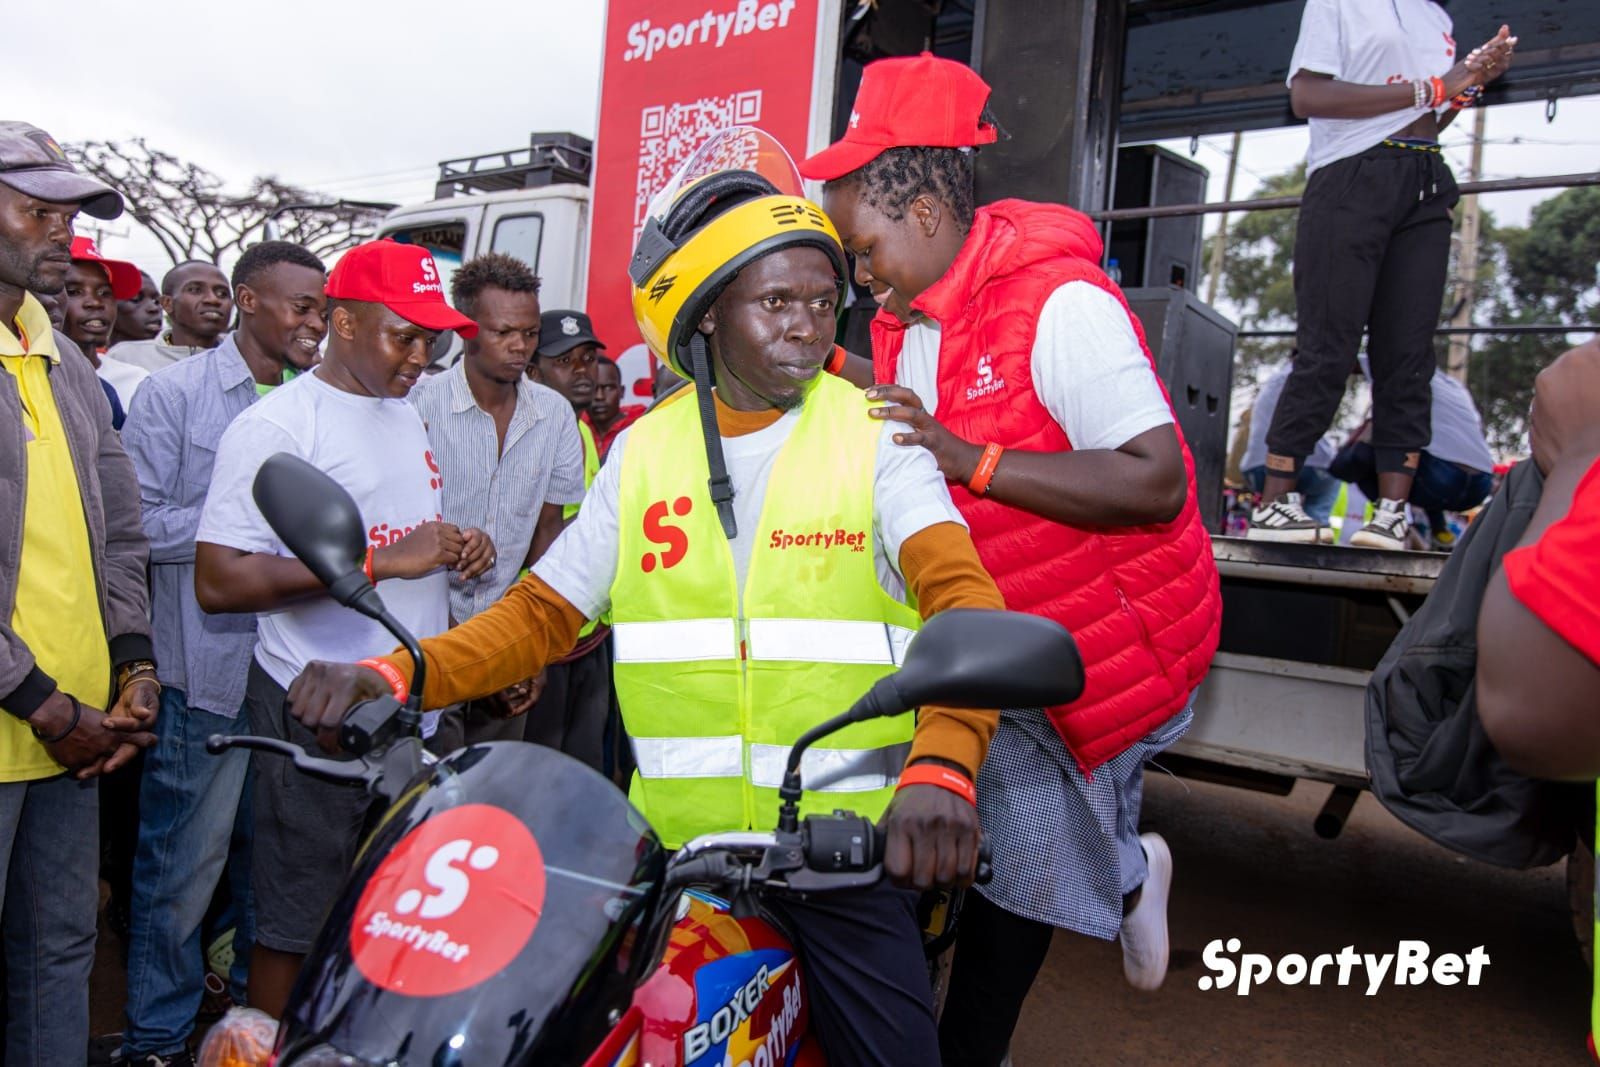
Chepterit Comes Alive As SportyBet Kenya Gifts Motorbike to Loyal Fans
Nest Lounge Narok Under Scrutiny as KRG The Don Shooting Incident Triggers Government Silence and Maasai Community Outcry