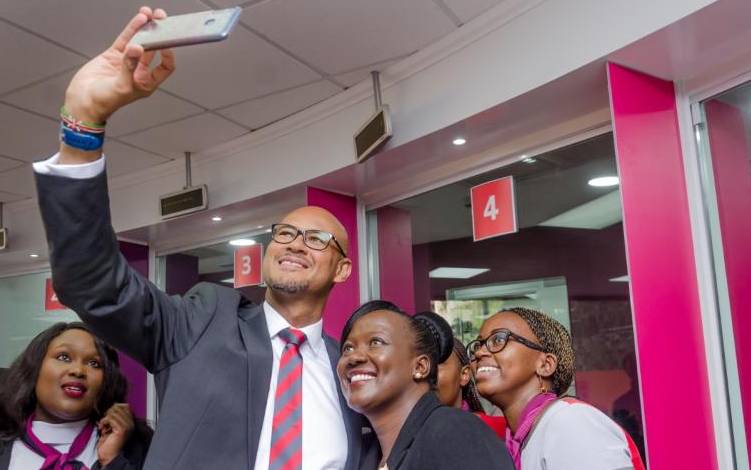
Absa Bank Kenya PLC Managing Director Jeremy Awori takes a selfie with staff at the Sarit Centre branch during the official unveiling of the Absa brand in Kenya on 10 February 2020.
Business News
First-quarter growth attributed to increased interest earnings and lower costs.
SEE ALSO: Top court’s verdict an antidote to revenue woes facing counties
Non-funded income grew from Sh2.7 billion to Sh2.9 billion. However, ABSA Kenya, formerly Barclays Kenya, did not factor a one-off Sh0.6 billion exceptional item related to spending towards the transition to Absa. This left it with a normalised profit after tax of Sh2.3 billion for the period ended 31 March 2020, which is a growth of 13 per cent compared to a similar period last year. The lender experienced a 75 per cent growth in impairment, which was offset by a drop in expenses. Growth in impairment was largely attributable to a few specific client names, said Absa. “The bank costs were well managed at Sh4.1billion reflecting a five per cent reduction year on year largely because of spending discipline and cost saves initiatives. The cost saves initiatives included automation of the processing centres, investment in alternative channels and branch rationalisation programmes,” said Absa Kenya Chief Executive Jeremy Awuori.SEE ALSO: Why KRA collected more tax in April despite virus
Liquid assets Mr Awuori noted that these savings were used to fund sustainable investments, especially in automation and digitisation. Totals assets grew by 10 per cent year on year, driven by growth in customer loans, investments in government securities as well as other liquid assets. Net customer loans were up 12 per cent to close at Sh203 billion, driven by key focus products namely general lending, trade loans, mortgage and scheme loans that recorded strong growth year on year. Customer deposits grew by seven per cent to Sh239 billion, with transactional accounts making up 66 per cent of the total deposits.SEE ALSO: Why KRA collected more tax in April despite coronavirus
Awuori noted that the level of uncertainty relating to the Covid-19 crisis is high and unprecedented this will have a negative impact on businesses globally, including the banking industry in Kenya. “The banking industry will feel the covid impact from April and most likely continue throughout the year.”Related reporting
More Business News →
High Court Blocks Oigara Bank Fraud Probe as Stanbic CEO Escapes Questioning

15 Proven Ways to Make Money Online in Kenya; No Scams!
High Court Halts Equity Bank's Takeover Bid on Swafi Foods in Landmark Ruling
